A new credit-scoring option is changing the mortgage industry. For loan officers, it could mean more opportunities to qualify borrowers, improve loan options, and turn previously challenging files into successful closings.
For decades, mortgage professionals have relied on traditional FICO scoring models to evaluate borrowers seeking conventional home loans. But the mortgage industry is undergoing one of its most significant credit-scoring changes in years.
With VantageScore 4.0 now available to approved lenders selling loans to Fannie Mae and Freddie Mac, loan officers have another tool to evaluate borrowers who may have struggled under traditional scoring methods.
At Credit Law Center, we believe this development represents an important opportunity for our Loan Officer Referral Partners. However, it also reinforces something we’ve emphasized for years: A different credit score doesn’t eliminate the importance of an accurate credit report.
Understanding these changes—and knowing when to involve an experienced credit law firm—could make a meaningful difference in helping more clients achieve home ownership.
A Major Shift in Mortgage Lending
According to an October 12, 2026, Wall Street Journal report, A Credit-Score Shift at Fannie and Freddie Is Shaking Up the Mortgage Market, the introduction of VantageScore 4.0 is already influencing how major mortgage lenders evaluate and price loans.
The transition gained momentum throughout 2026 as the Federal Housing Finance Agency (FHFA) expanded access to VantageScore 4.0.
Major lenders have responded in different ways:
- Rocket Mortgage adopted VantageScore 4.0 as its preferred scoring model.
- United Wholesale Mortgage began evaluating both traditional FICO and VantageScore, using the higher eligible score.
- PennyMac expanded VantageScore implementation across its lending operations.
The early numbers are noteworthy.
Rocket Mortgage reportedly reviewed approximately 1.4 million credit reports and found that VantageScore 4.0 scores averaged 11 to 12 points higher than traditional mortgage FICO scores.
Additionally, mortgage volume associated with VantageScore loans purchased by Fannie Mae and Freddie Mac reportedly grew from approximately $8 million in April to nearly $4 billion in August 2026.
That growth suggests lenders are beginning to recognize the potential advantages of having another credit-scoring option.
For loan officers, the takeaway is simple: Borrowers who previously fell short of a qualifying credit-score threshold may deserve another look.
However, a higher score doesn’t automatically mean better pricing or guaranteed loan approval. Lender guidelines, underwriting requirements, and investor considerations still matter.
For additional background, see Fannie Mae and Freddie Mac Open VantageScore 4.0 to All Lenders.
Understanding the Difference: Classic FICO vs. VantageScore 4.0
For years, mortgage lenders have generally relied on three traditional FICO models:
| Credit Bureau | Traditional Mortgage Score |
|---|---|
| Experian | FICO Score 2 |
| TransUnion | FICO Score 4 |
| Equifax | FICO Score 5 |
These older scoring models evaluate a borrower’s credit history differently from many of the scores consumers see through credit-monitoring applications.
VantageScore 4.0 introduces a more modern approach, incorporating additional information that can potentially benefit certain borrowers.
Key Differences Loan Officers Should Understand
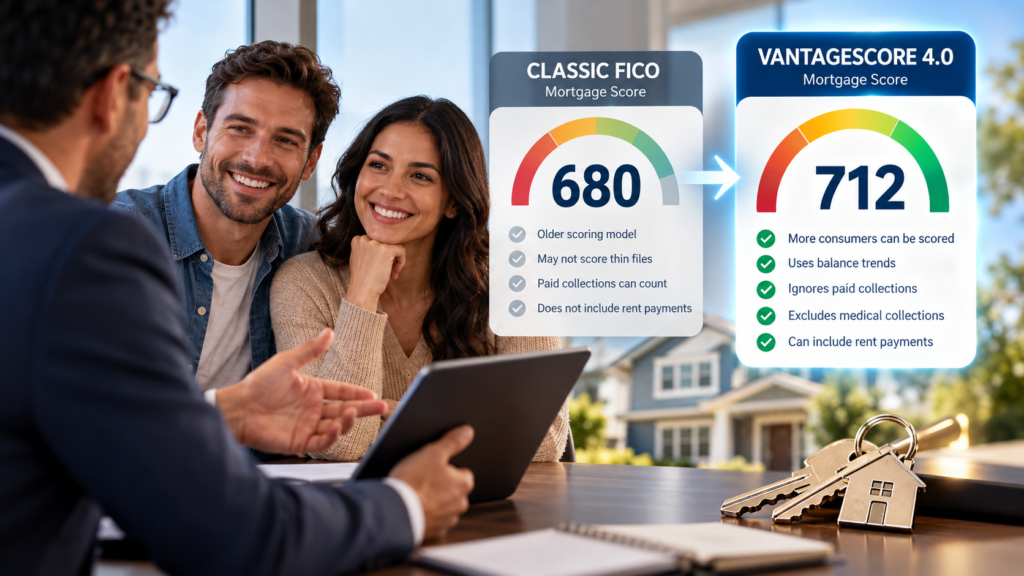
| Credit Factor | Classic Mortgage FICO | VantageScore 4.0 |
|---|---|---|
| Credit history | Generally requires at least six months of history | Can score some consumers with substantially shorter histories |
| Credit card balances | Primarily evaluates reported balances at a point in time | Can incorporate historical balance trends |
| Paid collections | May continue affecting scores | Generally excludes paid collection accounts |
| Medical collections | Treatment varies by reporting and model rules | Excludes medical collections from scoring |
| Rental history | Generally not incorporated | Can consider qualifying rental information reported to credit bureaus |
| Credit bureau models | Uses different FICO versions at each bureau | Uses a consistent scoring model across all three bureaus |
The important distinction is that VantageScore 4.0 may recognize positive credit behavior that older mortgage scoring models do not fully capture.
That could make a difference for borrowers with limited credit histories, improving debt-management habits, or certain collection-account histories.
But there is a critical distinction between credit scoring and credit reporting.
A scoring model determines how information is evaluated. It does not determine whether the information appearing on a credit report is accurate.
And that’s where Credit Law Center can become an important resource for your borrowers.
Three Opportunities Loan Officers Should Be Watching
1. Borrowers With Limited Credit Histories
Think about the first-time home buyer who has a steady job, consistent income, and responsible financial habits but lacks a lengthy credit history.
Traditional mortgage scoring models may have difficulty generating a score for these consumers.
VantageScore 4.0 can potentially evaluate borrowers with shorter credit histories, creating additional opportunities for some applicants who previously had difficulty establishing mortgage credit eligibility.
For loan officers, this could mean revisiting certain borrowers who were previously considered unscorable.
2. Borrowers With Paid Collections
Under traditional mortgage FICO models, paying a collection account doesn’t necessarily remove its negative scoring impact.
VantageScore 4.0 generally excludes paid collections from its calculations.
That difference may benefit borrowers who have already resolved collection accounts but continue to experience the effects of their past credit challenges.
However, an important point remains: Paying a collection does not automatically remove the account from a credit report.
Even when a particular scoring model ignores a paid collection, the underlying account information may still be visible and relevant to certain underwriting decisions.
Credit Law Center helps consumers evaluate whether collection accounts and other negative credit-reporting information are accurate, complete, and compliant with applicable consumer protection laws.
3. Borrowers Working to Reduce Credit Card Debt
VantageScore 4.0 incorporates trended credit information, allowing it to consider how certain balances have changed over time.
For example, a borrower who has steadily reduced credit card balances over several months may demonstrate a different credit-risk profile than someone whose balances have consistently increased.
This provides loan officers another reason to encourage clients to begin preparing their credit well before they are ready to purchase a home.
It also creates opportunities for ongoing communication with borrowers who aren’t quite mortgage-ready today but may become stronger applicants with time.
The Opportunity—and the Risk—of Relying on a Higher Credit Score
One of the most interesting developments involves how VantageScore 4.0 and traditional FICO scores are treated in mortgage pricing.
Initially, the newer scoring model faced pricing adjustments reflecting differences between the models.
However, the FHFA subsequently moved toward a unified pricing approach.
As reported by HousingWire in its coverage of the FHFA’s move to one pricing grid, this development allows lenders to evaluate pricing using either eligible scoring model without the earlier model-specific adjustment.
That could create meaningful opportunities for borrowers whose VantageScore is higher than their traditional FICO score.
But loan officers should be careful not to confuse a higher score with a guaranteed lower interest rate.
Loan pricing still depends on numerous factors, including loan-to-value ratio, loan structure, lender pricing, underwriting requirements, and investor risk assessments.
The best approach is to evaluate the borrower’s complete financial picture rather than relying on a single number.
Why Accurate Credit Reporting Still Matters More Than Ever
This is where Credit Law Center believes loan officers have an opportunity to strengthen their borrower relationships.
Imagine working with a borrower who has sufficient income, stable employment, and the financial ability to purchase a home.
But their credit report contains:
- An account incorrectly reporting late payments.
- A collection account that doesn’t belong to them.
- Duplicate negative account information.
- An account with an inaccurate balance or payment status.
- Information resulting from identity theft.
- Inconsistent or inaccurate information between credit bureaus.
A different scoring model might improve that borrower’s score, but it doesn’t automatically correct inaccurate information.
And inaccurate information can continue creating problems throughout the mortgage process.
A borrower cannot fully benefit from a credit-scoring model if the underlying credit information is wrong.
At Credit Law Center, our focus is on helping consumers identify and challenge inaccurate, incomplete, or otherwise legally disputable information appearing on their credit reports.
As a law firm working with federal consumer protection laws, including the Fair Credit Reporting Act (FCRA) and Fair Debt Collection Practices Act (FDCPA), we understand the legal responsibilities of credit reporting agencies, furnishers, and debt collectors.
Our role isn’t to promise a particular score or mortgage approval. It’s to help consumers exercise their rights when credit-reporting problems interfere with their financial goals.
For loan officers, that can mean having a knowledgeable resource available when credit-reporting issues are standing between a borrower and a potential home purchase.
FICO 10T: Another Change Loan Officers Should Watch
VantageScore 4.0 isn’t the only modern credit-scoring model attracting attention.
FICO 10T has also been approved as part of the broader effort to modernize mortgage credit scoring.
Like VantageScore 4.0, FICO 10T incorporates trended credit data to provide additional insight into borrowers’ financial behavior.
However, implementation timelines have evolved, and the model has not yet been introduced as an available conventional mortgage scoring option in the same way as VantageScore 4.0.
The Federal Housing Finance Agency and government-sponsored enterprises continue to work through implementation requirements.
Meanwhile, the FHA has announced plans involving alternative scoring models, including VantageScore 4.0 and FICO 10T, with a January 1, 2027, implementation target.
For additional information, review Freddie Mac’s Credit Score Models and Reports Initiative and the ICBA’s coverage of FHA’s alternative credit score implementation.
Loan officers should continue monitoring lender-specific requirements and agency announcements as these changes develop.
What We Recommend to Our Loan Officer Referral Partners
At Credit Law Center, we see these developments as an opportunity for mortgage professionals to take a more proactive approach to borrowers’ credit challenges.
First, revisit borrowers who were previously just outside qualifying score requirements.
A borrower who fell short under traditional mortgage scoring may have a different outcome under VantageScore 4.0, depending on the lender and loan program.
Second, encourage borrowers to review their credit reports early.
Identifying inaccurate information before a borrower enters the mortgage process can provide additional time to investigate and pursue appropriate corrections.
Third, recognize the difference between a credit challenge and a credit-reporting violation.
Not every negative account is inaccurate, and not every low credit score involves a legal issue.
However, when inaccurate or improperly reported information appears on a consumer’s credit report, that borrower may have rights and remedies under federal law.
Fourth, build a reliable referral relationship for borrowers who need credit-reporting assistance.
Loan officers are experts at helping consumers navigate mortgage financing. Credit Law Center focuses on consumer credit-reporting rights and disputes.
Those complementary areas of expertise can help borrowers better understand their options and prepare for future mortgage opportunities.
A Strong Referral Partnership Is About More Than One Closing
Every loan officer has encountered a borrower who wasn’t quite ready to purchase a home.
Perhaps their score was below a lender’s requirement. Maybe a collection account created complications. Or an unexpected negative item appeared during the application process.
Too often, those borrowers leave the mortgage conversation without a clear path forward.
At Credit Law Center, we believe those conversations should represent an opportunity to build long-term relationships—not simply a lost transaction.
When appropriate, referring a borrower for a professional credit-report review can help identify potential reporting inaccuracies and give the consumer a better understanding of their rights.
It also allows the loan officer to remain connected to that borrower while they work toward their home ownership goals.
The objective is straightforward: help borrowers address legitimate credit-reporting problems while keeping the door open for future mortgage opportunities.
Let’s Help More Borrowers Move Toward Home Ownership
The arrival of VantageScore 4.0 is another reminder that the mortgage industry continues to evolve.
Scoring models will change. Underwriting technology will improve. New opportunities will emerge for borrowers who may have struggled under older systems.
But one principle remains unchanged:
Accurate credit reporting is an essential foundation of responsible mortgage lending.
At Credit Law Center, we value our relationships with mortgage professionals who share our commitment to helping consumers move toward financial stability and home ownership.
Whether you’re already a Credit Law Center Loan Officer Referral Partner or you’re exploring a relationship with our firm, we welcome the opportunity to work together.
Have a borrower whose mortgage opportunities may be affected by inaccurate credit reporting?
Connect with Credit Law Center to learn how our team can assist with evaluating potential credit-reporting issues and helping consumers understand their rights.
Credit Law Center — Helping Protect Consumer Credit Rights and Supporting the Professionals Who Help Make Home Ownership Possible.
Visit www.creditlawcenter.com to learn more about our services and referral partnerships.
Industry Sources and Further Reading
- A Credit-Score Shift at Fannie and Freddie Is Shaking Up the Mortgage Market — The Wall Street Journal via Yahoo Finance, October 12, 2026.
- Fannie Mae and Freddie Mac Open VantageScore 4.0 to All Lenders — Informative Research.
- Freddie Mac: Credit Score Models and Reports Initiative — Freddie Mac.
- FHA Releases Date and Guide for Alternative Credit Score Models — Independent Community Bankers of America, September 11, 2026.
- FHFA Moves to One Pricing Grid — HousingWire.
Credit Law Center provides legal services related to consumer credit-reporting matters. Results depend on individual circumstances. Credit Law Center does not guarantee credit-score increases, account removals, mortgage qualification, or loan approval. Mortgage professionals should confirm current scoring and underwriting requirements with their lenders and applicable agencies.
